

Dollarwise: Budget & Tracking
HammerMedia
- 3.3
- 1.15K Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
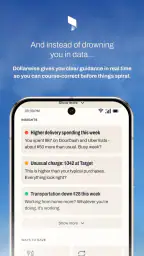
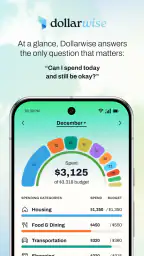
Dollarwise: Budget & Tracking Pros and Cons
Pros
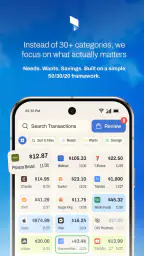
- Clear spending categories make it easy to identify where your money goes.
- Custom budgets help you set limits for different areas of your daily spending.
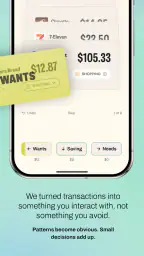
- Simple tracking encourages more consistent financial habits over time.
- Useful summaries give you a quick view of your overall financial progress.
- Suitable for beginners who want basic budgeting without complex tools.
Cons
- Some advanced features may require a paid subscription.
- Manual transaction entry can become time-consuming for frequent purchases.
- Limited investment and debt-management tools may not suit advanced users.
- Budget accuracy depends on keeping every transaction updated.
- Privacy-conscious users may want more detail about data handling and security.
 Analysis by All-app
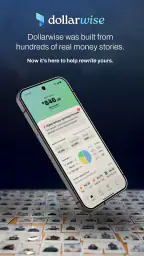
I approached Dollarwise: Budget & Tracking as someone who wanted a calmer way to understand everyday spending, not as someone looking for a complicated financial command center. It is a free finance app from HammerMedia, aimed at helping users make sense of their money through budgeting and tracking. The idea is simple: give your spending a clearer shape so decisions feel less random.
That simplicity is both its appeal and its main limitation. Dollarwise works best when you are willing to enter information consistently and use it as a regular checkpoint. It is not a substitute for a bank account, financial adviser, or detailed accounting platform. I found it more useful as a personal money journal with structure: a place to see habits, set boundaries, and turn vague concern into a practical next action.
The app is available at no upfront cost and is rated for Everyone, which makes it approachable for students, households, and people starting their first serious budget. Its average rating is 3.3 from around 2,200 ratings, so I would not present it as universally loved. That mixed response is worth keeping in mind: the concept is accessible, but the experience depends heavily on how much detail and automation you expect from a finance tool.
What to expect before you build a budget
The first thing I would tell a new user is to lower their expectations in the right way. Dollarwise is not most valuable because it magically discovers where your money goes. Its value comes from helping you create a repeatable view of your spending. You still need to provide enough information for that view to mean anything.
That makes it a good fit for someone who often says, “I should probably check my spending,” but never gets around to organizing it. The app gives that intention somewhere to go. Instead of opening a spreadsheet, deciding on categories, and designing formulas, you can begin with a focused money-tracking routine.
I would be more cautious if you need direct bank synchronization, investment analysis, shared household controls, tax preparation, or business bookkeeping. Those needs call for a more specialized product. Dollarwise is better understood as a lightweight budgeting companion. If you want a clear personal snapshot and are comfortable taking an active role, it has a sensible purpose.
The developer, HammerMedia, positions the product around changing the way you think about money rather than presenting finance as a technical exercise. In practice, that means the app makes most sense when you use it to support decisions: whether to buy something today, whether a recurring expense still fits, or whether a category is quietly taking over your month.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Who will get the most from it
I can see Dollarwise helping a first-time budgeter who feels intimidated by finance apps. It is also useful for someone moving from mental notes to a written system, especially when the main problem is not a lack of income but a lack of visibility. A person saving for a short-term goal may also appreciate having a place to compare everyday choices with the larger plan.
It is less suitable for users who refuse manual attention. A budget that is never updated becomes a guess, and no interface can fix that. I would also skip it if your finances involve several accounts, multiple currencies, complex reimbursements, or detailed reporting requirements. In those cases, the simplicity that helps beginners may feel restrictive.
Getting started without making the setup overwhelming
My advice is to begin with a narrow first pass rather than trying to recreate your entire financial life immediately. Start with the money you actually want to understand this week. That could mean regular household spending, food, transport, or discretionary purchases. A smaller starting scope makes the first useful result arrive sooner.
During setup, think in terms of decisions rather than perfect categories. If two categories would lead you to make the same choice, they probably do not need to be separate yet. For example, splitting every type of takeaway purchase may create more maintenance than insight. A broader category can be more useful if it tells you whether you are approaching a limit.
At the same time, avoid making one enormous category for everything. The point of tracking is to reveal patterns, and a category that contains groceries, subscriptions, leisure, and transport will hide the very behavior you are trying to see. I found the best balance comes from choosing a handful of categories that match real decisions in your routine.
One practical setup method is to identify fixed commitments first, then add flexible spending. Fixed commitments are the costs that are difficult to change immediately. Flexible spending is where small choices accumulate. This order helps prevent a common beginner mistake: setting an attractive spending target before accounting for the money that is already committed.
Another useful habit is to decide when you will update the app. I prefer a short check after a purchase or a single review at the end of the day, depending on how busy the day is. Waiting until the end of the month may feel easier, but it also makes forgotten purchases and vague amounts more likely. Dollarwise rewards consistency more than occasional bursts of enthusiasm.
Your first meaningful success
The first success should not be a perfect budget. It should be one clear discovery. After entering enough recent spending to represent your normal routine, look for a category that is larger or more frequent than you expected. That observation is more valuable than building an elaborate plan you will not maintain.
For example, imagine checking the app after an ordinary workweek and noticing that convenience purchases are appearing repeatedly. The useful response is not necessarily to ban them. You might set a realistic boundary, choose specific days for them, or prepare an alternative for the moments when convenience usually wins. The app becomes useful when its information changes a decision outside the app.
I recommend making one small adjustment after that first review. Choose a change that is measurable without being miserable: delay one nonessential purchase, set aside a modest amount before spending, or review a recurring charge you no longer value. Then return to the app after several days and see whether the change was realistic. This creates a feedback loop rather than a one-time budgeting exercise.
A less obvious benefit of this approach is that it separates awareness from self-judgment. If the numbers look uncomfortable, the first question should be whether the categories and entries reflect reality. Only after that should you decide what needs changing. Otherwise, it is easy to react to an incomplete picture and create a budget that feels punitive from the beginning.
How I would use it in an ordinary week
Suppose I am paid at the beginning of the week and know that several regular expenses are due soon. I would first use Dollarwise to outline the money that is already spoken for. Then I would leave a clear view of what remains for flexible choices. Before making a larger discretionary purchase, I could check whether it fits the remaining room instead of relying on the balance in my bank account alone.
That distinction matters because a bank balance can look healthy while hiding upcoming commitments. A tracking app cannot replace the bank’s transaction record, but it can encourage a different question: “What portion of this money is genuinely available?” For a beginner, that mental shift may be more important than a sophisticated chart.
At the end of the week, I would review only the categories that affected my choices. If transport was normal but food spending was unexpectedly high, there is no reason to spend time analyzing every other area. This selective review keeps the routine manageable and prevents the app from becoming another task that you abandon.
Where new users may become confused
The most common confusion with a budgeting tool like this is the difference between tracking what happened and planning what should happen. A recorded expense describes the past. A budget boundary describes an intention. They work together, but they are not interchangeable. If your plan looks healthy while your entries are incomplete, the plan is not giving you reliable reassurance.
Another point that can trip people up is timing. A purchase may belong to the day it happened, the period when it will be paid, or the month you personally use for planning. Pick one consistent method and stick with it. Changing the rule halfway through makes comparisons difficult and can make a normal spending pattern look unusual.
Recurring expenses also deserve careful attention. They are easy to overlook because they do not feel like fresh decisions each time. I would review them separately from everyday purchases and ask whether each one still earns its place in the budget. This is one of the highest-value checks a beginner can make because a single recurring cost can affect every future review.
Do not assume that a polished summary automatically means the underlying information is complete. If a number surprises you, inspect the entries behind it before changing your whole plan. Missing a few small purchases can distort a category, while placing an expense in the wrong category can create an equally misleading story.
Practical ways to make the routine stick
One technique I found helpful is to use Dollarwise at the moment a decision feels uncertain, not only during a scheduled review. If I am debating an unplanned purchase, checking the relevant category can turn an emotional decision into a visible trade-off. That does not mean always saying no; it means understanding what the purchase displaces.
A second technique is to keep the first budget deliberately forgiving. A plan that leaves no room for ordinary variation will fail quickly, and failure often leads people to stop tracking altogether. It is better to create a boundary that reflects real life, then tighten it after you understand your pattern.
A third is to treat unusual expenses as information rather than as evidence that the entire system is broken. A birthday, repair, or travel day may not fit the normal pattern. Record it in a way that keeps it visible, but do not let one unusual event define your everyday target. This is where personal judgment matters more than any automatic summary.
There is also a useful trade-off between detail and speed. More categories can answer more precise questions, but they demand more attention. Fewer categories are easier to maintain, but they may hide useful differences. I would start broad, then split a category only when you repeatedly need to know what is inside it.
Free access, paid extras, and device expectations
Dollarwise can be installed for free, but it includes in-app purchases ranging from around fifteen dollars to nearly five hundred dollars per item. That is a wide range, so I would pay close attention to any purchase screen before confirming anything. A free download does not mean every part of the experience is free, and users should be especially careful if they are only looking for basic tracking.
The app is currently listed as version 6.4.0 and requires Android 7.0 or newer. That makes it accessible on many older Android devices, although your personal experience can still depend on the phone’s performance and software environment. It has passed the threshold of over 100,000 installs, which suggests that it has reached a meaningful audience without making popularity a guarantee of fit.
Because this is a finance app, I would also approach data entry deliberately. Avoid rushing through setup just to reach the main screen. A few minutes spent deciding what you want to monitor will make later reviews clearer. If you are uncomfortable maintaining financial information in a mobile app, a local spreadsheet or handwritten system may feel more appropriate, even if it takes more effort.
How it compares with familiar alternatives
Compared with a spreadsheet, Dollarwise is easier to approach because you do not have to design the structure yourself. A spreadsheet remains stronger for custom formulas, unusual income patterns, and detailed historical analysis. I would choose the spreadsheet when I need complete control, but I would choose Dollarwise when the main challenge is starting and continuing.
Compared with a banking app, Dollarwise serves a different purpose. A banking app is the authoritative place to view account activity and balances. Dollarwise is more useful for turning that activity into a personal spending plan. I would not use it as a replacement for checking the bank, and I would not assume that a budget view eliminates the need to verify transactions at the source.
Compared with a full-featured finance manager, Dollarwise may feel less demanding and therefore easier to keep using. The trade-off is that users who want extensive account connections, investment views, or detailed household collaboration may outgrow it. In my view, the right choice depends less on which app has more features and more on which system you will actually update.
Who should continue, and who should move on
I would recommend giving Dollarwise a fair trial if you are new to budgeting, want a straightforward way to track personal spending, or need a visual reminder of limits you have set for yourself. The strongest result is likely to come from using it for one focused purpose first, such as controlling discretionary spending or preparing for a short-term goal.
I would move to another option if you need automatic, highly detailed financial aggregation, complex reporting, or a system shared by several people with different responsibilities. I would also reconsider it if manual tracking repeatedly becomes a burden. A budgeting method is only useful when its maintenance cost is low enough to survive busy weeks.
The mixed 3.3 average rating suggests that expectations matter. Someone wanting a simple starting point may appreciate the direct approach, while someone expecting a complete financial dashboard may feel disappointed. I think the app should be judged as a practical tracking aid rather than as an all-purpose money platform.
My next-step recommendation
If you install it, do not begin by trying to solve every financial problem. Create a small, honest view of your current routine, record enough activity to make the picture meaningful, and use the result to make one decision. That first decision might be adjusting a category, questioning a recurring cost, or setting a limit that reflects reality.
After that, keep the review habit short. A few focused minutes are more valuable than a long session followed by weeks of silence. If the app helps you notice one pattern early enough to act on it, it is doing its job.
My final view is that Dollarwise: Budget & Tracking is most convincing as a beginner-friendly checkpoint for personal spending. It is free to start, broadly accessible, and simple enough to support a first budgeting routine, but its usefulness depends on honest entries and realistic expectations. The real strength is not automatic financial magic; it is turning vague money worries into a next action you can actually take.
Frequently Asked Questions
What is Dollarwise: Budget & Tracking used for?
Dollarwise: Budget & Tracking is designed to help you organize personal finances in one place. After setting up your income, recurring bills, spending categories, and savings goals, you can monitor where your money goes and compare your actual spending with your budget. It is especially useful for users who want a straightforward overview rather than a complicated investment or banking platform.
Does Dollarwise connect directly to my bank account?
Whether Dollarwise connects to your bank depends on the version, region, and available integrations. Before entering sensitive information, check the app’s current privacy details and supported connection methods in the official store listing. If automatic bank synchronization is unavailable, you can still use the app by adding income and expenses manually, although regular updates will require more effort.
Is Dollarwise: Budget & Tracking free to download and use?
Dollarwise may be available as a free download, but some features can be restricted behind in-app purchases or a subscription. Premium options may include expanded tracking tools, additional categories, reports, customization, or an ad-free experience. Review the pricing page carefully before starting a trial, and confirm the renewal terms so you are not surprised by a recurring charge.
Is my financial information safe in Dollarwise?
You should review Dollarwise’s privacy policy, permissions, and data-handling information before using it for personal financial records. Avoid sharing banking passwords unless an official, secure connection is clearly provided, and use a strong device passcode. Manual entries may reduce account-linking concerns, but the app can still store sensitive spending details, so privacy settings and account security remain important.
Can I use Dollarwise to manage shared or family finances?
Dollarwise can be useful for planning household spending if it supports shared budgets, multiple profiles, or data export in your current version. However, users should confirm these features before relying on the app for joint finances. If there is no collaboration option, one person may need to maintain the records manually, which can make synchronization and responsibility for updates more difficult.


